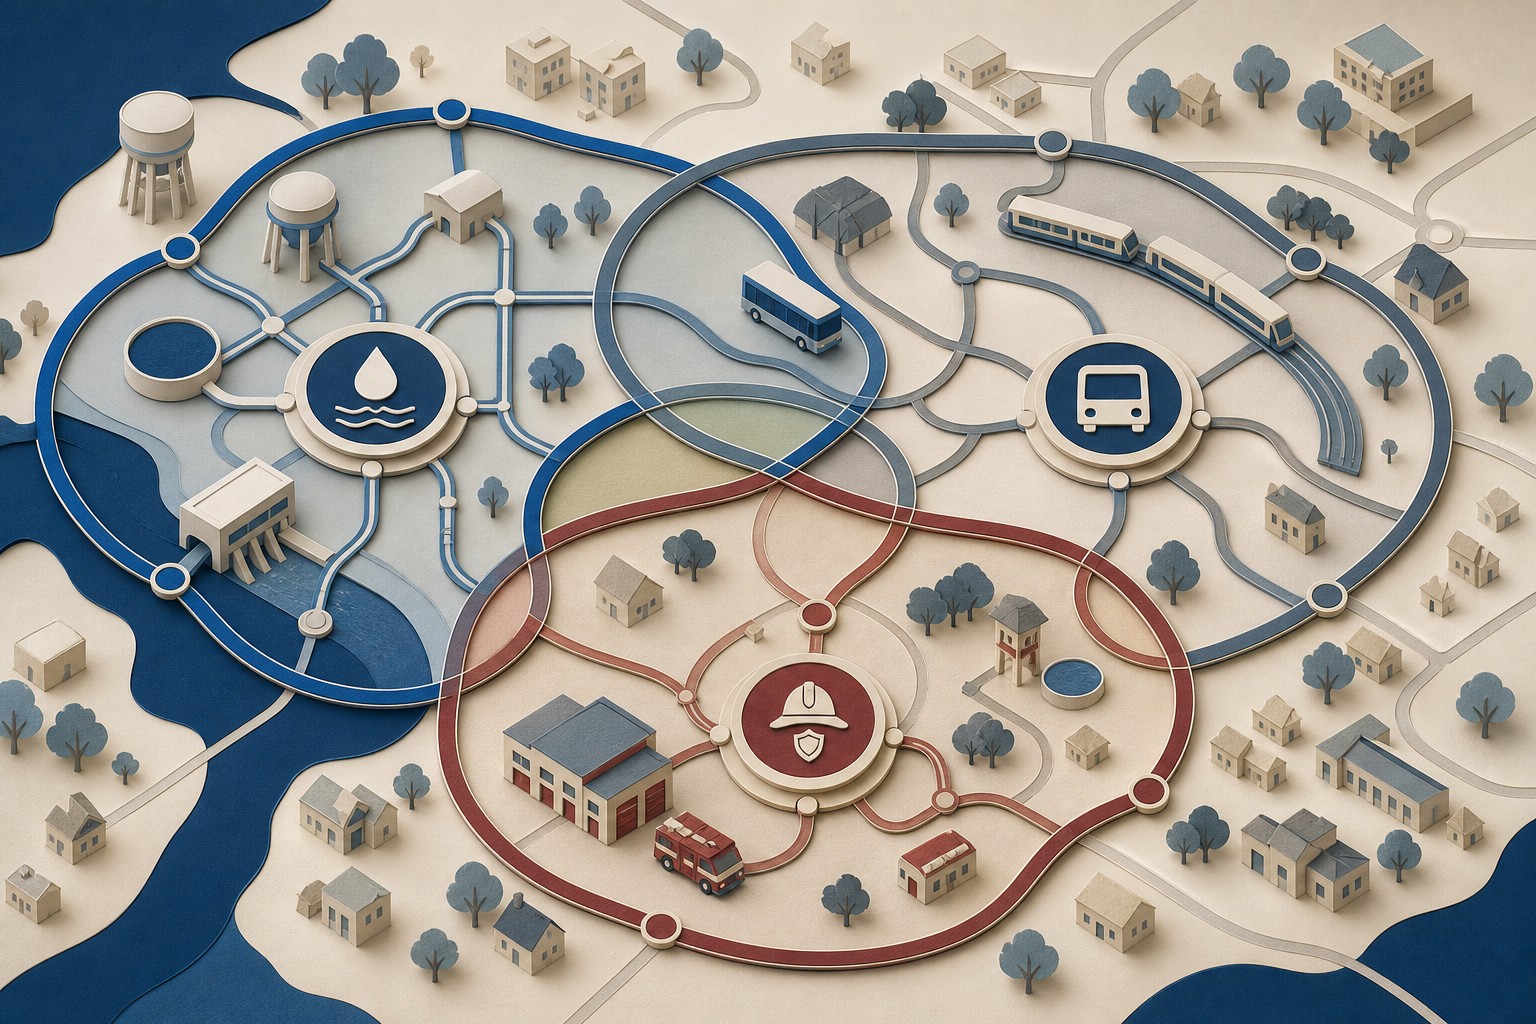
Your city may not be the public entity that provides every local service. Water, transit, fire protection, libraries, parks, drainage, or other functions can involve an organization called a district, authority, board, or commission.
Some of these organizations qualify as separate special district governments. Others are departments or dependent agencies of another government. The name alone does not settle the question.
§ A limited purpose is the starting point
For U.S. Census classification, special district governments are organized local entities outside the county, municipal, township, and school-district categories. They are authorized by state law to provide one or a limited number of designated functions and must have enough administrative and fiscal autonomy to qualify as separate governments.
That is a statistical and organizational definition, not a universal grant of powers. State law determines how districts are formed, governed, financed, changed, or dissolved.
An entity can perform a public function without meeting the autonomy test for separate-government status.
§ Build a five-part identity card
When a special district appears in a bill, budget, or meeting notice, identify five things.
Function: What service or facility is it authorized to provide?
Boundary: Which properties or residents fall within its service or taxing area? Service boundaries may differ from city or county lines.
Autonomy: Can it make substantial administrative and fiscal decisions independently, or is it controlled by another government?
Governing body: Who appoints or elects the board, and who adopts its budget and policies?
Revenue authority: Which taxes, fees, assessments, grants, transfers, service charges, or debt can it use under applicable law?
None of those answers should be assumed from the word “district.”
§ Why boundaries can be confusing
A household can be inside a city, county, school district, and several limited-purpose service areas at the same time. Those entities may have different boards, fiscal years, meeting schedules, and documents.
This does not mean every property is served by every kind of special district. Nor does it mean each district has taxing authority. Census state descriptions show that organization differs substantially across states.
The local tax flow guide explains why local public money may pass through several governments rather than one city account.
§ How to find the district's public records
Start with the official website or state registry. Look for the enabling law or formation document, service-area map, board roster, meeting calendar, adopted budget, fee or tax material, annual financial report, audit, and debt disclosures.
Confirm whether the entity is separate or presented within another government's financial statements. A component unit may have distinct governance but still appear in a broader reporting entity under accounting rules.
If the district name appears on a notice, use the contact information on that official document rather than relying on a similarly named organization elsewhere.
Finance provides another identity check. A district may charge for services, receive intergovernmental assistance, levy a tax or assessment when authorized, issue debt within applicable limits, or use a combination of sources. None of those powers belongs to every district. Match each revenue to the enabling law, adopted budget, rate or levy document, and annual report. If another government collects an amount on the district's behalf, collection does not necessarily make that government the service provider or final decision-maker.
The same care applies to debt and assets. Determine which entity owns the facility, which entity owes the obligation, and which revenue is pledged before connecting a project to a district.
§ Accountability follows the actual structure
The right accountability question depends on who holds authority. A board may approve rates or budgets. A parent government may appoint members or retain approval power. State agencies may oversee reporting, elections, debt, or service standards.
Public participation also varies. Meeting laws, hearing requirements, election methods, and records access come from the applicable jurisdiction. A generic article can help locate the process but cannot define it for every district.
§ Questions to bring to the documents
Ask which law created the entity, whether it is classified as a separate government, who selects the governing body, what boundary applies, which revenues are authorized, where the budget and audit are posted, and which government would answer if the district could not act alone.
Those questions turn an unfamiliar name into a clear institutional map.
§ Follow the service to the responsible entity
Special districts remind us that “local government” is plural. A service may be local without belonging to city hall. State law, autonomy, boundaries, governance, and revenue authority reveal who is responsible.
The Insights library contains more guides for connecting local institutions with their budgets and public records.
§ Sources and further reading
- U.S. Census Bureau — Government Organization and Structure Glossary
- U.S. Census Bureau — Individual State Descriptions
- U.S. Census Bureau — About the Government Units Survey