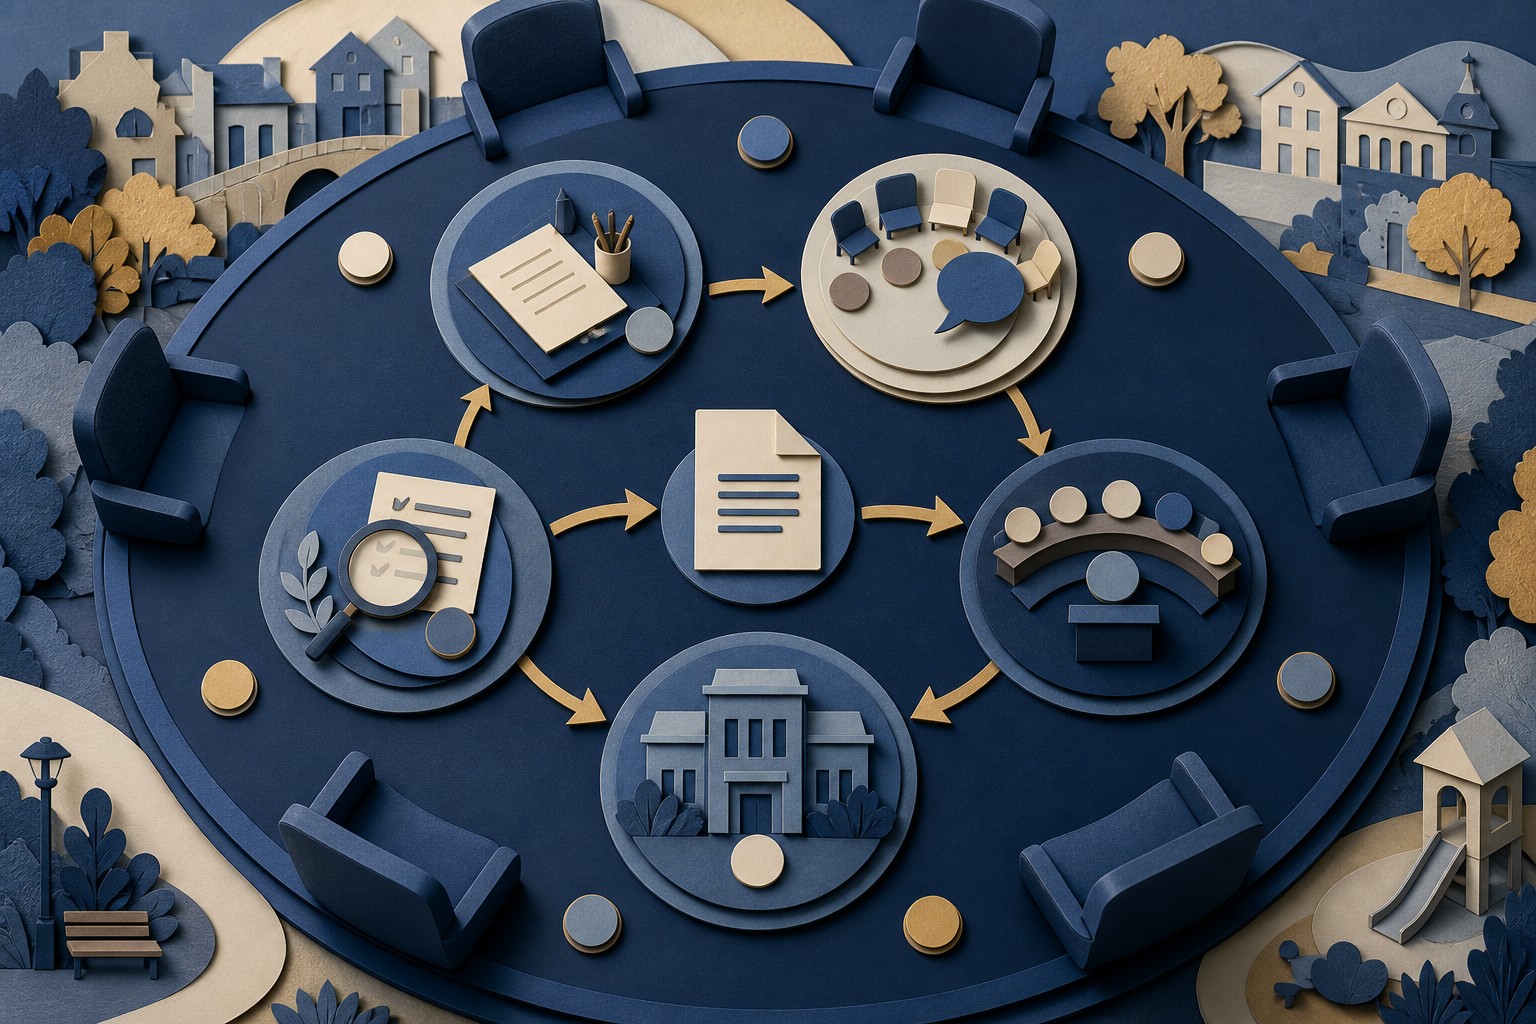
“Who decided to spend this money?” sounds like a question with one name as the answer. In local government, the decision usually moves through several roles.
Staff may develop a proposal. An executive or administrator may recommend priorities. A governing body may authorize appropriations. Departments administer programs. Auditors and the public review what happened. The titles and legal powers vary, but separating the roles helps residents find the right decision point.
§ A proposal is not yet spending authority
Departments often begin by identifying service needs, staffing, contracts, maintenance, or capital projects. Finance staff assemble estimates and revenue assumptions. A mayor, manager, administrator, superintendent, or executive team may shape a proposed budget, depending on the government.
These steps matter, but a proposal is not necessarily final authority. It tells the public what is recommended and why. Read the transmittal letter, budget message, department requests, and staff reports to see which choices were made before formal deliberation.
§ The governing body usually holds a formal authorization role
Under applicable state and local law, a council, commission, board, or other governing body commonly adopts the budget or appropriations through an ordinance, resolution, or comparable action.
The body may amend the proposal, set conditions, approve rates or levies within its authority, and authorize contracts or capital items at separate meetings. The exact division of power is not uniform. Some actions require voter approval, another agency, or a procedure outside the annual budget.
The city budget guide explains why an adopted budget is both a financial plan and an authorization framework.
§ Public input enters at defined points
Public meetings, hearings, written comments, advisory committees, and ballot measures can influence decisions. They do not all have the same legal effect.
A hearing creates a formal opportunity to receive testimony; it does not automatically transfer the final vote from the governing body to the audience. A ballot measure can be binding when law requires voter authorization. An advisory committee may recommend without adopting.
Find the notice, agenda, staff report, and applicable rules before participating. Ask whether the item is informational, proposed, amendable, or scheduled for final action.
§ Adoption does not decide every later transaction
An appropriation authorizes spending up to a defined level and purpose under local rules. It does not necessarily select every vendor, approve every invoice, or guarantee that the full amount will be spent.
Departments and procurement officials carry out authorized work within policies, contracts, and controls. Some contracts return to the governing body; others fall within delegated authority. Unexpected conditions may require a budget amendment or separate approval.
This distinction protects both accountability and administration: elected or appointed bodies set authorized boundaries, while officials carry out many operational steps.
§ Oversight asks what happened afterward
Budget monitoring reports compare current activity with the plan. Annual financial reports present reported results after the period. Audits examine financial reporting, compliance, controls, or performance according to their scope.
Oversight bodies may include auditors, finance committees, inspectors, state agencies, governing boards, and the public. No single document answers every question. Authorization, implementation, and results belong to different records.
Timing also changes who can act. Before adoption, a resident may be able to comment on priorities or proposed amounts. After adoption, the practical question may concern a contract award, delegated administrative decision, or amendment. After the year closes, the question shifts again toward reported results and oversight. Reviewing the agenda label and current document prevents a policy request from being directed to an auditor, or an implementation complaint from being treated as if the budget had never been authorized.
Money can also pass through more than one governing body. A city may participate in a regional authority, receive a grant from another government, or contract with a special district. In those cases, one body may authorize the local contribution while another approves the program budget. Trace the agreement and each entity's agenda before assigning the entire decision to one meeting.
§ Find your point in the decision chain
For a proposed expenditure, ask:
- Who developed and recommended it?
- Which body has authority to approve it?
- When can the public review or comment?
- Is the current item a plan, appropriation, contract, or report?
- Who administers the spending after approval?
- Which later document will show the outcome?
These questions are more useful than assuming the loudest official made every decision.
§ Local structure changes the names, not the need for clarity
Oregon's official local-budget guidance, for example, distinguishes preparation by a budget officer, review by a budget committee, a public hearing, and adoption by a governing body. Washington guidance describes its own statutory roles and procedures. These are illustrations of state-specific systems, not national templates.
For your community, use its charter, state law, budget calendar, agendas, and adopted documents.
§ Follow the decision, not only the dollar
Public money moves through authority as well as funds. Understanding who proposes, authorizes, administers, and reviews a choice makes participation more timely and oversight more precise.
The Insights library offers additional guides to the documents at each stage.
§ Sources and further reading
- Oregon Department of Revenue — Local Budget Law
- Oregon Department of Revenue — Local Budgeting Manual
- Washington State Auditor — Budget Process
- U.S. Census Bureau — Government Organization Glossary